

Dave - Fast Cash & Banking
Dave Operating LLC
- 4.4
- 225.83K Reviews
- 10.00M
- Downloads
- Free
- Price
Screenshots
Dave - Fast Cash & Banking Pros and Cons
Pros
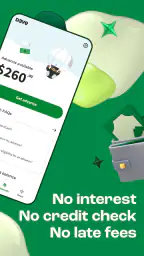
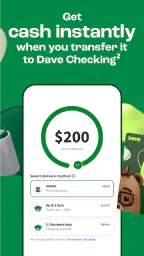
- Instant cash advances available anytime
- No credit check required for cash advances
- Seamless integration with bank accounts
- No hidden fees or late charges
- User-friendly interface and navigation
Cons
- Limited to U.S. residents only
- Monthly membership fee is required
- Cash advances have a capped limit
- No interest earned on account balance
- Customer support response can be slow
 Analysis by All-app
The first week with Dave - Fast Cash & Banking is easy to understand: it puts short-term cash support alongside everyday money management, rather than treating a cash advance as the whole product. I find that combination useful when a bill lands at an awkward point in the pay cycle. Still, the real test is not whether the app feels reassuring on day one, but whether its tools become part of a steady routine without encouraging me to rely on advances to cover ordinary spending.
Where the first-week appeal comes from
Dave is a finance app from Dave Operating LLC. Its main appeal is practical: the app brings together a way to request an advance, account and spending information, and options intended to help users find extra income. The app is free to download, rated for Everyone, and has a 4.4 average from around 567,000 ratings. More than 10 million installs suggest it has reached a wide audience, but popularity alone cannot tell me whether it suits someone’s budget.
What I would look for during the first few days is not just the advance screen. I’d check how clearly the app presents my account activity and what steps it asks me to take before I make a financial decision. A useful habit is to review the upcoming bills and current balance together, then decide whether the shortfall is temporary or part of a recurring pattern. That distinction matters: a one-off timing gap is different from a budget that is consistently short.
Month-to-month value depends on the routine
The app has a better chance of earning a lasting place if I use it as a regular check-in rather than opening it only when money is tight. For example, after payday I can review planned expenses, then look again before a major bill is due. If I use an advance, I’d also note how repayment fits into the next pay period. That simple step helps prevent a quick fix from making the following week harder.
Dave may be most useful for people with income that arrives on a predictable schedule but whose bills do not line up neatly with payday. Someone whose hours or income vary sharply may need a more flexible cash-flow plan, since a short-term advance does not make an uncertain monthly budget predictable. For ongoing planning, I’d still keep a separate budget or spreadsheet if I need detailed categories, shared household tracking, or a long view of savings goals.
Maintenance, limits, and sensible expectations
There is some upkeep involved in any app that draws on account information: I’d review the linked details periodically, check transactions for accuracy, and pay attention to notifications rather than assuming they replace my own calendar. If an alert appears close to a bill date, I would verify the amount and due date with the biller. A reminder can help me notice a deadline, but it cannot decide which expense should take priority.
Cash advances can also create a habit that is hard to break if I treat them as extra income. Before accepting one, I’d ask whether the next deposit can cover both normal expenses and repayment. If the answer is no, borrowing may move the pressure forward instead of solving it. People looking for long-term debt relief, a full-service bank relationship, or detailed financial advice may be better served by a different tool or a qualified adviser.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
A Friend in Financial Need
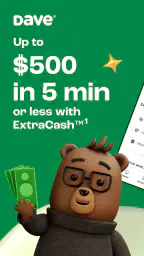
Dave isn’t just another banking app; it’s more like a buddy who’s got your back when you’re short on cash. You know those times when unexpected expenses pop up? That’s when Dave swoops in with instant cash advances of up to $500. No interest, no credit checks, just a small tip if you feel like it. How cool is that?
Banking Made Simple
Signing up was a breeze. I linked my existing bank account, and boom, I was all set. The app interface is straightforward, and navigating through it feels like a walk in the park. You’ve got your balance, upcoming expenses, and cash advance options all laid out neatly. Plus, with notifications for upcoming bills, it’s like having a personal assistant reminding you to pay those pesky utility bills.
Budgeting Tools That Make Sense
Now, here’s where Dave really shines. It’s not just about lending you money; it helps you manage it, too. With its automatic budgeting feature, you can track your spending and see where your money goes each month. It categorizes expenses, so you know if you’re spending too much on takeout or splurging on online shopping. It’s like having a financial planner without the hefty fees.
Member-Only Benefits
Joining the Dave community comes with perks. From helping you build your credit score with their unique credit-building tool to offering side gigs through their app to earn extra cash, Dave is all about supporting your financial health. It’s like they’re saying, “Hey, we’ve got more ways to help you out!”
And if you’re someone who’s concerned about your carbon footprint, Dave partners with Trees for the Future to plant a tree for every percentage of tips received. So, you’re not just helping yourself, but the planet too!
How it compares with familiar money tools
Compared with a standard banking app, Dave puts more emphasis on bridging cash-flow gaps and surfacing ways to earn, while a traditional bank app is usually the clearer choice for managing an established account and its core services. Compared with a standalone budgeting tool, Dave’s appeal is that cash access and spending visibility sit in the same experience. The trade-off is that anyone who wants deep forecasting, custom household categories, or a broad view across several financial institutions may prefer a dedicated budgeting product.
One practical workflow is to treat the app as a signal, not as the final authority on a decision. I’d check its view of spending, then compare that with my bank balance and scheduled payments before taking action. Categorization can reveal patterns, but a category label may not capture why a purchase happened or whether it was unusual. A quick monthly review of the transactions that look out of place can make the summaries more useful than simply glancing at totals.
Everyday use without creating more pressure
Imagine a utility bill is due a few days before payday and a necessary car expense has already reduced the balance. I’d first confirm the bill date, check what other payments are scheduled, and decide whether the gap is genuinely temporary. If an advance seems appropriate, I would make a repayment plan at the same time rather than treating approval as proof that the money is affordable. If the next pay period is already committed, contacting the biller or reviewing nonessential spending may be safer than adding another obligation.
This is also why I would not use Dave as a substitute for an emergency fund. A small reserve, even one built gradually, gives more room to handle irregular expenses without borrowing against the next pay cycle. The app can support awareness and access, but it cannot make a recurring shortfall disappear. If advances become necessary every month, that is a cue to revisit fixed costs, income timing, or available community and professional support instead of simply repeating the same transaction.
Who is likely to keep it installed?
I can see the strongest fit for someone who wants a simple, phone-based way to monitor cash flow and occasionally handle a short timing mismatch. The app may also appeal to a person who values having work-finding options alongside money tools, rather than switching between several services. It is less compelling for someone who already has a comfortable buffer, prefers to keep financial accounts separate, or wants a detailed planning system that covers long-term goals and shared expenses.
Before relying on any advance, I’d read the in-app terms carefully and check the total effect on the next pay period. “No interest” does not mean every possible choice is cost-free or that repayment has no impact on the budget; optional tips and the timing of cash access deserve attention. I’d also make sure notifications are helpful rather than noisy by acting on the ones tied to real due dates and reviewing the rest during a planned money check-in.
Final Thoughts
After spending some time with Dave - Fast Cash & Banking, it’s clear why it’s a lifesaver for many. It’s like having a financial safety net that’s always there to catch you when you fall. The blend of instant cash, budgeting tools, and eco-friendly initiatives makes it a standout app in today’s crowded financial app market. If you’re looking for a way to manage your finances smartly and sustainably, give Dave a go. You might just find it’s the financial friend you never knew you needed.
For me, the strongest reason to keep it installed would be recurring usefulness in checking cash flow, not the novelty of an advance. The current version, 3.88.2, follows an app first released on April 24, 2017, so this is an established finance product rather than a brand-new experiment. My recommendation is measured: try it if its mix of short-term support and everyday money tools matches a real need, but build a routine around checking repayment and spending. If you mainly want a conventional bank account or a comprehensive budget planner, another option may fit better.
Frequently Asked Questions
What is Dave - Fast Cash & Banking, and what services does it offer?
Dave - Fast Cash & Banking is a financial app designed to help users manage their money more efficiently. It offers features such as cash advances, budgeting tools, and checking accounts without overdraft fees. The app aims to provide fast, hassle-free access to cash and assist users in avoiding unexpected bank fees.
How does the cash advance feature work in the Dave app?
The cash advance feature in the Dave app allows users to borrow a small amount of money, typically up to $100, without interest. This service is meant to help users cover unexpected expenses between paychecks. Users must link their bank account to qualify, and the app will analyze their income patterns to determine eligibility.
Are there any fees associated with using Dave - Fast Cash & Banking?
While Dave itself does not charge interest on cash advances, there is a monthly membership fee of $1. Additionally, users can choose to leave an optional tip when receiving a cash advance. It's important to note that using external ATMs might incur fees, which are not covered by Dave.
Is Dave - Fast Cash & Banking safe to use for managing my finances?
Yes, Dave - Fast Cash & Banking prioritizes user security and employs encryption to protect your personal information. The app uses secure connections to your bank and does not store login credentials. However, users should always ensure they download the app from trusted sources and keep their device secure.
Can I use Dave - Fast Cash & Banking outside the United States?
Currently, Dave - Fast Cash & Banking is only available to users within the United States. The app requires a U.S. bank account to function, and its services are tailored to the U.S. financial system. Users outside the U.S. will not be able to sign up or use the app's features.


